$10,000 starting principal — Family A (median Black-family wealth ≈ $44k in 2022 SCF; we round down for clean math).
$1,000,000 starting principal — Family B (top-decile household, >$1.94M threshold in 2022 SCF; $1M is a clean round number for the math, not a fictional ceiling).
r = 0.07 — long-run real (inflation-adjusted) S&P 500 return, ≈ 7% over 50+ years.
t = 40 years — one career-to-retirement horizon.
Continuous formula: A = Pert; e0.07·40 = e2.8 ≈ 16.44.
Family A → $10,000 · 16.4446 ≈ $164,446.
Family B → $1,000,000 · 16.4446 ≈ $16,444,647.
Ratio: still 100×. Absolute gap: from $990,000 at year 0 to $16,280,200 at year 40.
Cited data points
Median white family wealth $284,310 vs. median Black family $44,100 vs. median Hispanic $62,120 (2022 Federal Reserve SCF). FRB note, Oct 2023
CT Baby Bonds (2023–). $3,200 invested at birth for every CT child born to Medicaid families. Projected $11k–$24k at age 18. ~16,000 children seeded in FY24. NCRC
American Opportunity Accounts Act (Booker / Pressley). $1,000 at birth + up to $2,000/yr means-tested; accessible at 18. Hamilton/Darity model projects this would close ~92% of the racial wealth gap at age 18. CAP · Pressley one-pager
MA BabySteps (2020–). $50 seed at birth into a 529; +$10/mo for first year for SNAP families ($170 total). Tiny seed, large opt-in scale. Mass.gov
2021 expanded Child Tax Credit. Monthly cash to families during 2021. Cut child poverty by 43% in one year. Lapsed; child poverty rose again in 2022. Columbia CPSP
Estate-tax threshold restoration. Returning the threshold from $13.61M (2024) toward the 2000 level of $675k or the 2009 level of $3.5M reaches more inheritances. The 2017 doubling exempted ~99.9% of estates from the tax. CRS
Trauma triage
Wealth gaps are a default-safe, systemic-level topic. Some students may have personal experience with debt, eviction, inheritance, or no inheritance. Frame the math as "starting principal," not "what your family is worth." Do not collect personal financial info. Opt-out for the agency-move discussion: students can pass.
The Number e
When does compounding stop speeding up — and what does that limit do to two families starting at very different places?
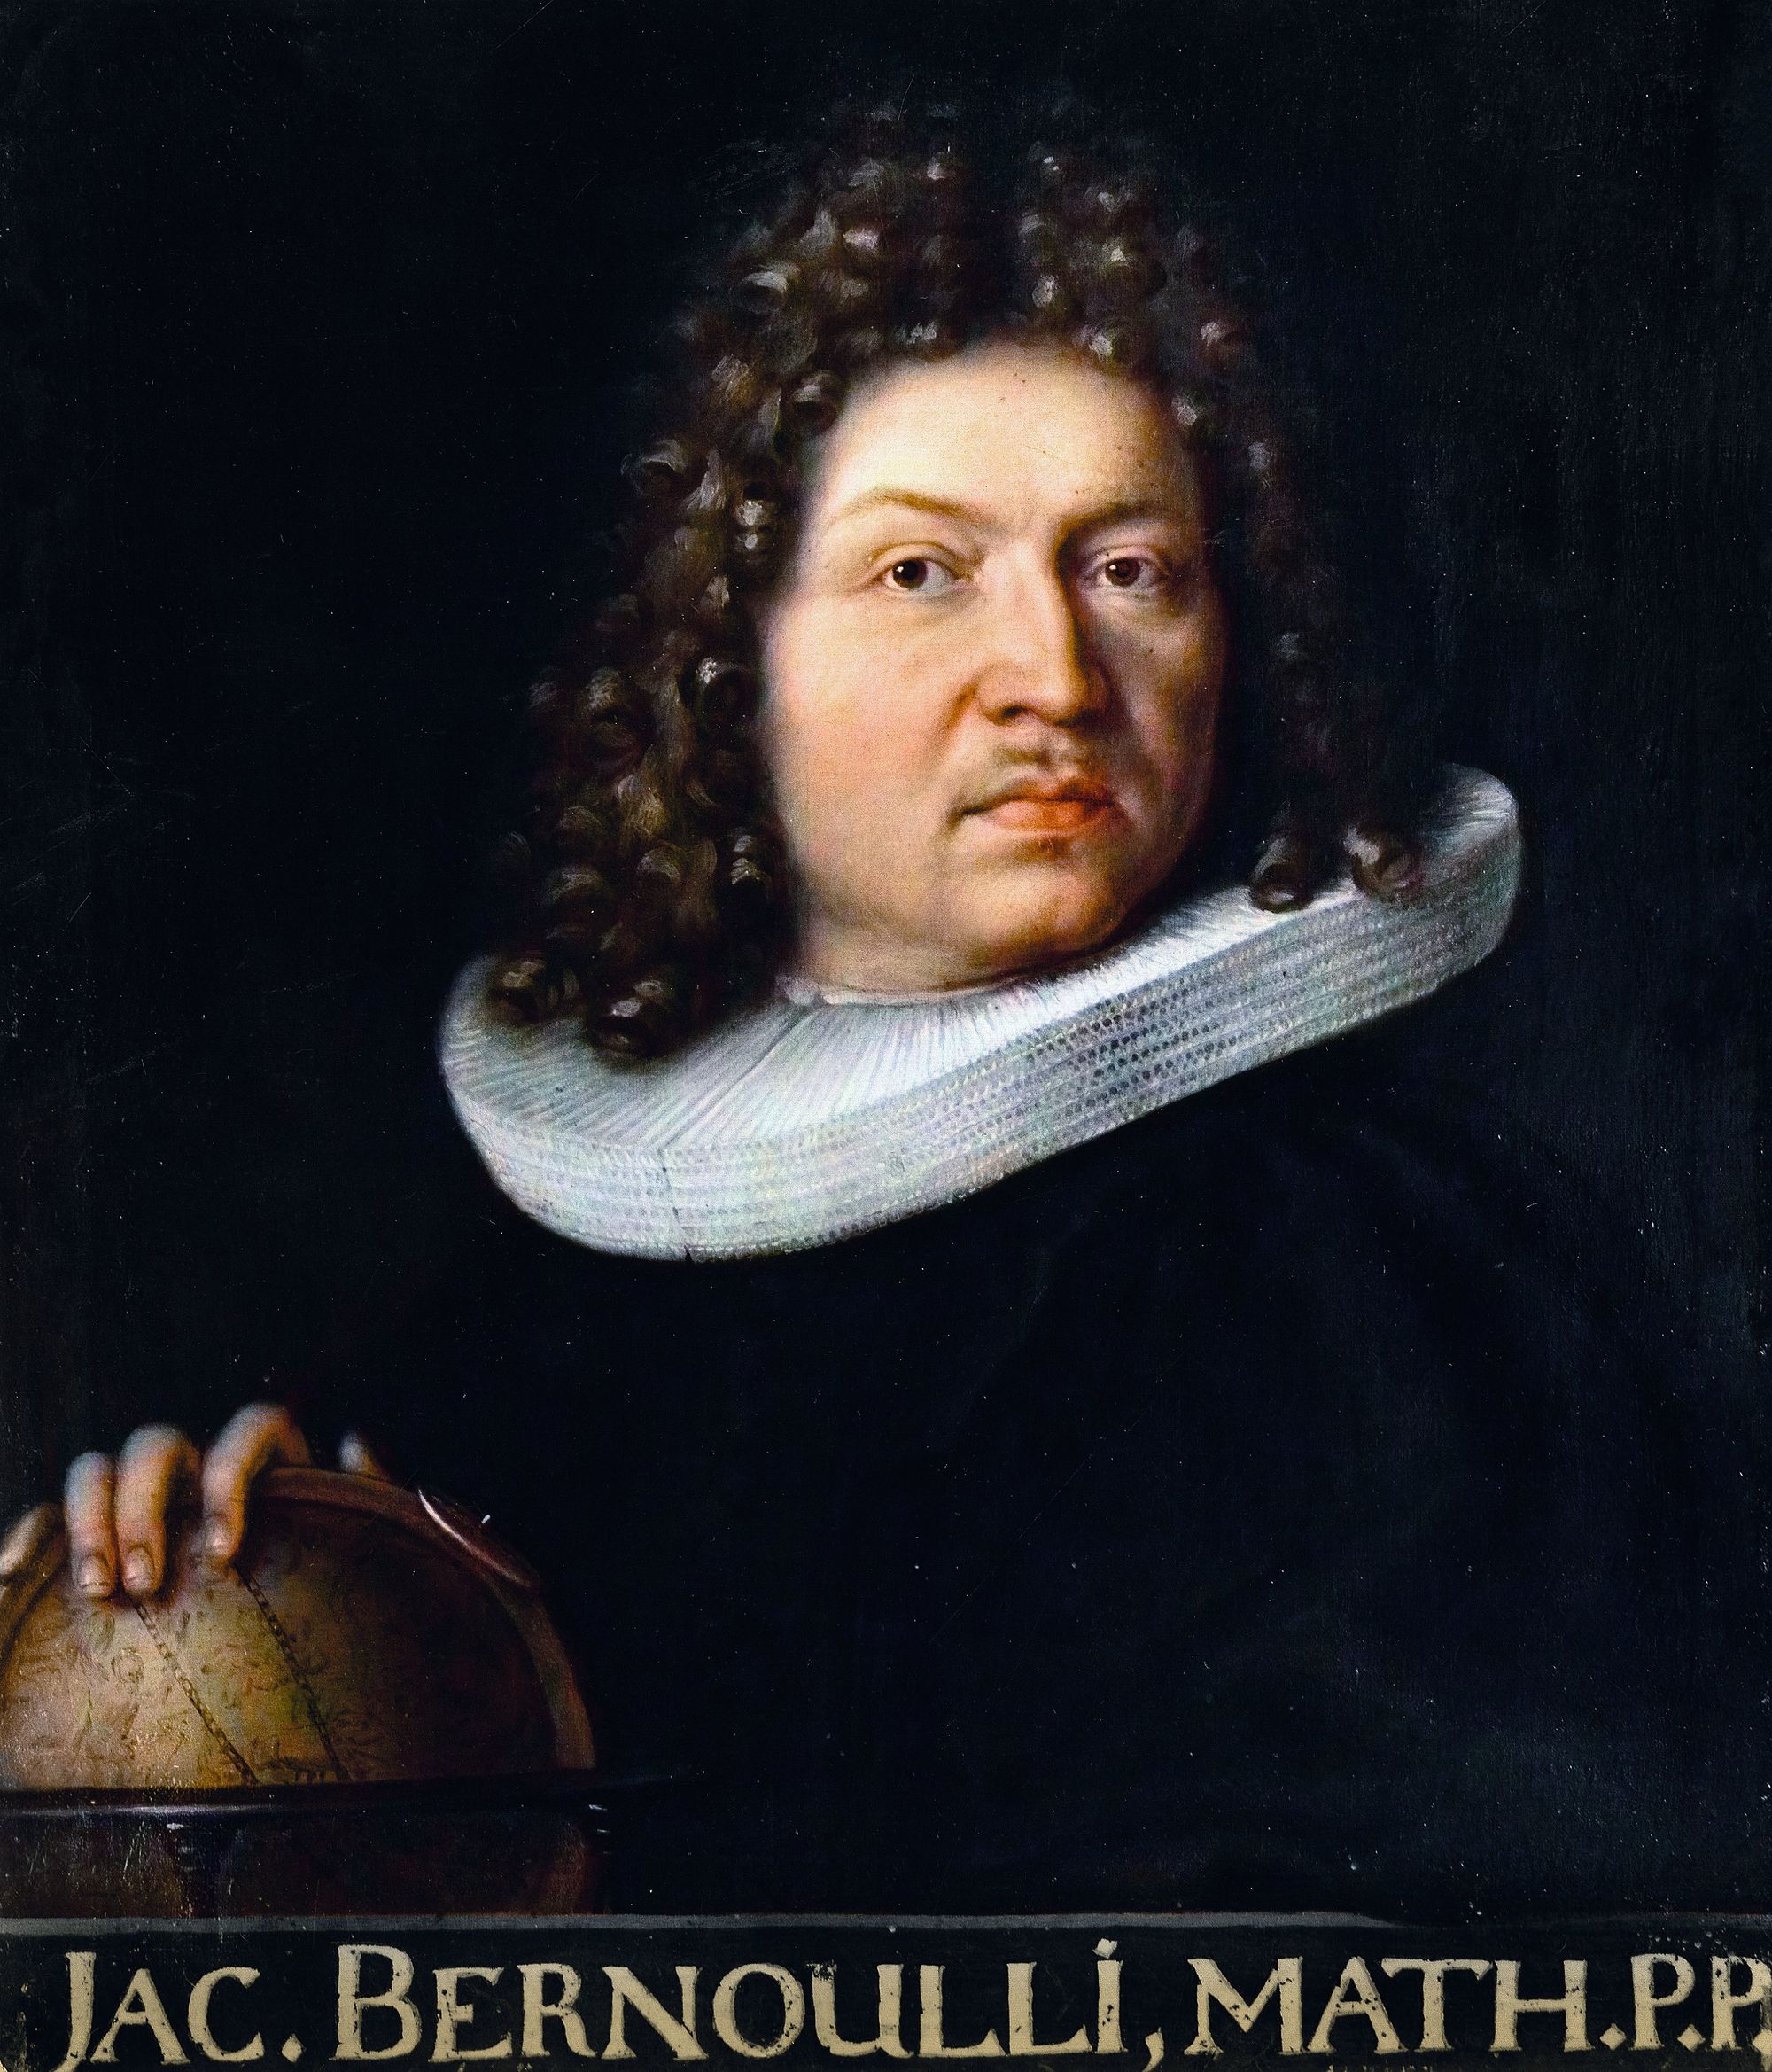
Jakob Bernoulli (1655–1705)
asked: if a bank pays 100% interest, does compounding it more often than once a year give you more money? In 1683, by compounding faster and faster, he found that the answer approaches a fixed limit — the number we now call e. Portrait by Niklaus Bernoulli, 1687. Public domain. Source: Wikipedia.
Big Question
What happens when you compound interest not annually, not monthly, not daily, but continuously — at every instant —
and is there a limit to how fast money can grow?
Standards: HSF-LE.A.4. Lesson 12 introduces the constant e. Students are not expected to construct functions with base e from scratch; they should be able to recognize e as a number (≈2.718) and interpret an expression like \(Pe^{rt}\). The wrench: today's compound-interest examples are not generic — they trace what happens to two families starting with $10,000 vs. $1,000,000 at the same return rate over 40 years. The math reveals that the multiplicative gap is preserved, and the absolute-dollar gap explodes.
Prep checklist
☐ Calculators or spreadsheets ready (one per pair).
☐ Open the Data + Intervention Packet drawer (top right of screen, teacher mode) before Activity 2.
☐ Trauma-aware: frame as "starting principal," never "your family's net worth." Students may opt out of the agency-move share.
Warm-Up5 min
Do Now
Match each situation to one of the four equations. One equation has no match.
Equations
\(f(t) = 400 \cdot 2^{t/10}\)
\(g(t) = 400 \cdot 0.75^{t/10}\)
\(h(t) = 400 \cdot 0.5^{t/10}\)
\(j(t) = 400 \cdot 1.25^{t/10}\)
Situations
A bacteria population starts at 400 and doubles every 10 hours. t = hours.
The half-life of a radioactive element is 10 years; sample starts at 400 g. t = years.
A fish population of 400 grows by 25% per decade. t = years.
5 min. Students work alone for 2 min, then pair-share for 1 min. Press them: "Where in the equation can you read the growth or decay factor? Where can you read the time unit?"
The unmatched equation is B (\(0.75^{t/10}\)) — we will use it to set up Activity 1's question.
Do not resolve the matches yet — that's the next slide.
Warm-Up · Synthesis3 min
Same form, different bases
All four equations have the same shape: \(400 \cdot b^{t/10}\). The number that changes — the base b — tells the whole story. Today we will meet a base that is none of these.
Situation 1 (bacteria doubling):Equation A: \(f(t) = 400 \cdot 2^{t/10}\). Doubles every 10 hours ⇒ base 2, time unit 10.
Situation 2 (radioactive half-life):Equation C: \(h(t) = 400 \cdot 0.5^{t/10}\). Halves every 10 years ⇒ base 0.5.
Situation 3 (fish population, +25%/decade):Equation D: \(j(t) = 400 \cdot 1.25^{t/10}\). Grows 25% per decade ⇒ base 1.25.
Equation B (\(0.75^{t/10}\)) has no match. Make up a situation it could describe.Sample: a beach loses 25% of its sand every 10 days. Anything that decays by 25% per decade-equivalent fits.
click to advance discussion ▶
Move quickly through the matches. The point is not getting the matches right — it's noticing that the base b carries the model. In Activity 1 we will meet a base that emerges naturally from compounding, not from "doubles every 10" or "halves every 10."
Activity 1 · Launch3 min
Bernoulli's Question (1683)
A bank pays you 100% interest per year on a deposit of $1.
If the bank credits the interest once at the end of the year, your $1 becomes $2.
But what if the bank compounds the interest twice a year — 50% added at the half, then another 50% on the new total? Or every month? Every day? Every second?
General compounding formula
\[A \;=\; P \cdot \left(1 + \frac{r}{n}\right)^{n t}\]
P = principal · r = annual rate · n = compounds per year · t = years
With \(P=1\), \(r=1\), \(t=1\) the formula becomes \(\left(1 + \dfrac{1}{n}\right)^{n}\). What do you predict happens as n gets very large? Does the dollar amount blow up to infinity, or does it level off?
3 min. Have one student read the setup aloud. Solicit predictions for the disc-prompt — do not resolve. Common student predictions:
Goes to infinity — the exponent grows without bound.
Stays at $2 — the base shrinks toward 1, so it cancels.
Levels off somewhere > 2 — correct intuition, the work-time will land it.
The point: two competing tendencies. The base \((1+\tfrac{1}{n})\) shrinks toward 1 (would push the result down toward 1), but the exponent n grows (would push the result up). Which wins? Activity 1 forces them to compute and decide.
Reference · How ToActivity 1 · Work Time10 min
Reference · How To — Compounding $1 at 100% for 1 year
Step
What to do
Example (n = 4, quarterly)
1
Identify n: how many times per year is the interest compounded?
Quarterly ⇒ n = 4.
2
Each period, the rate per period is \(\tfrac{r}{n} = \tfrac{1}{n}\). The base of the expression is \(1 + \tfrac{1}{n}\).
Raise the base to the n power — one factor for each compounding period.
\(1.25^{4} = 2.4414\).
★
Compare with \(n = 1\). Is the dollar amount larger or smaller?
\(n = 1\): \(\$2.00\). \(n = 4\): \(\$2.44\). More compounds ⇒ more money — for now.
Activity 1 · Work Time
Fill in the table. Use a calculator.
Compounding
n
\(\left(1+\tfrac{1}{n}\right)^{n}\)
Annually
1
2.0000
Semi-annually
2
?
Quarterly
4
2.4414
Monthly
12
?
Daily
365
?
Every second
31,536,000
?
What is the largest dollar amount you got — and which n produced it?
Predict: as n → ∞, does the value keep growing, level off, or oscillate?
10 min · Activity 1 Work Time. Leave on screen during work. Pair students; one calculator per pair is enough.
Expected fills: n=2 → 2.2500; n=12 → 2.6130; n=365 → 2.7146; n=31,536,000 → 2.71828 (calculator may show 2.7182817 or similar). Problem 1 target: ≈ 2.7183 (every-second), but only by a hair over daily. Problem 2 target: levels off — never crosses 2.72. Watch for: students entering \(1 + 1 \div n\) without parentheses around \((1 + 1/n)\). Calculator order-of-operations can drop the +1. Have them check by computing the n=4 row first — if they don't get 2.4414, fix the parentheses. Watch for: students who jump to "infinity" without computing — this is the productive surprise of the lesson.
Amplify · 4 inputs
Order: Text → Math Response (named answer1, answer2, answer3, answer4) → Note (CL in </>).
content:
  when answer1.submitted and answer1.numericValue > 2.249 and answer1.numericValue < 2.251
    "Correct! (1 + 1/2)^2 = 1.5^2 = 2.25."
  when answer1.submitted and answer1.numericValue > 2.999 and answer1.numericValue < 3.001
    "Almost — 3 looks like (1 + 1)^2 (forgot to divide 1 by n). Try (1 + 1/2)^2 = 1.5^2."
  when answer1.submitted and answer1.numericValue > 1.499 and answer1.numericValue < 1.501
    "That is just 1 + 1/2. You also need to raise it to the n = 2 power. Try (1.5)^2."
  when answer1.submitted and not isBlank(answer1.latex)
    "Hmm — the base is 1 + 1/n, not 1 + 1·n. With n = 2, base = 1.5, then square it."
  otherwise ""
Row 2: (1 + 1/12)^12
content:
  when answer2.submitted and answer2.numericValue > 2.6125 and answer2.numericValue < 2.6135
    "Correct! (1 + 1/12)^12 ≈ 2.6130. More compounds gave more money — but the gain over quarterly is small."
  when answer2.submitted and answer2.numericValue > 2.0832 and answer2.numericValue < 2.0834
    "Almost — 2.0833 is just 1 + 1/12. You need to raise it to the 12th power."
  when answer2.submitted and answer2.numericValue > 12.99 and answer2.numericValue < 13.01
    "That looks like 13 — maybe (1 + 12)^1? The base is 1 + 1/12 ≈ 1.0833, raised to the 12th power."
  when answer2.submitted and not isBlank(answer2.latex)
    "Almost — check parentheses on the calculator. Compute 1/12 first, add 1, then raise to the 12th power."
  otherwise ""
Row 3: (1 + 1/365)^365
content:
  when answer3.submitted and answer3.numericValue > 2.7144 and answer3.numericValue < 2.7148
    "Correct! (1 + 1/365)^365 ≈ 2.7146. Notice — between monthly (2.6130) and daily (2.7146), the dollar amount only grew by about 10 cents."
  when answer3.submitted and answer3.numericValue > 365 and answer3.numericValue < 367
    "I see what happened — that looks like (1 + 1)·365 or (1+1/365)·365. Use the exponent: raise (1 + 1/365) to the 365 power."
  when answer3.submitted and not isBlank(answer3.latex)
    "Hmm — the answer should be just over 2.71. Check parentheses: 1 + 1/365 first, then ^365."
  otherwise ""
content:
  when answer4.submitted and answer4.numericValue > 2.7180 and answer4.numericValue < 2.7186
    "Correct! Compounding every second gave you about $2.7183 — only a fraction of a cent more than daily. The growth is leveling off at a number just over 2.718."
  when answer4.submitted and answer4.numericValue > 2.999 and answer4.numericValue < 3.001
    "Hmm — 3 is too big. Compounding every second only adds a tiny amount over daily. The value should be just over 2.718, not 3."
  when answer4.submitted and not isBlank(answer4.latex)
    "Almost — your calculator may have rounding issues at very large n. The target is just over 2.7182. Did you get something close?"
  otherwise ""
Activity 1 · Synthesis5 min
The limit has a name
n
\(\left(1+\tfrac{1}{n}\right)^{n}\)
1
2.0000
2
2.2500
4
2.4414
12
2.6130
365
2.7146
31,536,000
2.71828…
n → ∞
e ≈ 2.71828…
Bernoulli (1683) computed this exact sequence and noticed it leveled off. He could not write down the limit as a fraction or root.
Fifty years later, Euler called the limit e. Like π, it is irrational — its decimal never repeats.
The constant e
\[\lim_{n\to\infty}\left(1+\frac{1}{n}\right)^{n} = e \approx 2.71828\]
Continuous compounding formula
\[A \;=\; P\,e^{r t}\]
Same letters as before. Use this when the bank (or the market) credits interest continuously — at every instant.
Try Saying
Compounding more often makes more money, but the gains shrink because ___.
5 min. Read down the table. The big move: compounding every second only beats daily by a fraction of a cent. There is a ceiling — the number e.
Tell students: e is "the natural compounding ceiling." It shows up everywhere in math, science, and finance for the same reason — whenever something grows in proportion to its current size, the rate of growth bumps into e.
The continuous formula \(A = Pe^{rt}\) is the headline. Activity 2 will use it on real principals.
Do not assess derivation of \(e\) from the limit; this lesson only requires that students know e ≈ 2.718 and can read \(Pe^{rt}\).
MASL · New Symbol
A new symbol: e
Math
\(e\)
We Say
"e"
Meaning
An irrational number, approximately 2.718. Like π, its decimal never repeats or terminates. e is the limit you get from compounding 100% interest more and more often.
Math
\(\left(1 + \dfrac{1}{n}\right)^{n}\)
We Say
"the quantity 1 plus 1 over n, raised to the n"
Meaning
As n grows large, this expression gets closer and closer to e. It is one way to define the number e.
Math
\(P e^{r t}\)
We Say
"P times e to the r-t"
Meaning
The amount you have after time t, starting with principal P, compounded continuously at rate r.
Read across each row left to right. Have one student read the Math, one read the We-Say, one read the Meaning. Same routine students know from earlier MASL slides.
Press: "What letters can change in \(Pe^{rt}\) and what stays fixed?" (Answer: P, r, t change; e is a constant just like π.)
Activity 2 · Launch3 min
Two Families, Same Rate, 40 Years
Two families invest in the same broad-market index fund and never touch it for 40 years. The S&P 500 has returned about 7% per year after inflation over the past 50 years. Treat the return as continuous: \(A = P\,e^{r t}\) with \(r = 0.07\), \(t = 40\).
Family A
Starts with $10,000. (Roughly the median Black family's wealth in 2022.)
Family B
Starts with $1,000,000. (Top-decile threshold; the 90th percentile of US household wealth was about $1.94M in 2022.)
Before computing — predict: at year 40, the gap between Family B and Family A in dollars will be (a) about $990,000 like at the start, (b) about $9.9 million, (c) about $16 million, or (d) something else?
3 min. Have students raise hands for (a), (b), (c), (d). Don't reveal yet. The framing question is "what does compound growth do to a gap?" not "what is the right answer?"
Trauma-aware framing: Use "starting principal" not "your family." If a student says "we don't have $10K to invest" — that's the lesson. The math we are doing assumes both families can invest. The next slide forces that assumption to do work.
Citations are in the Data + Intervention Packet drawer (top right, teacher mode). $10K and $1M are clean numbers, not literal medians.
Reference · How ToActivity 2 · Work Time10 min
Reference · How To — Continuous compounding
Step
What to do
Example: $5,000 at 5% for 20 yrs
1
Identify P, r, t.
P = 5000, r = 0.05, t = 20.
2
Compute the exponent r t first.
\(r t = 0.05 \cdot 20 = 1.00\).
3
Compute \(e^{r t}\) on a calculator. (Look for the \(e^{x}\) key.)
\(e^{1.00} \approx 2.7183\).
4
Multiply by P.
\(5000 \cdot 2.7183 \approx \$13{,}591\).
★
The growth multiplier \(e^{r t}\) is the same for any starting principal.
\(\$1\) becomes \(\$2.72\). \(\$1{,}000\) becomes \(\$2{,}718\). The factor is the same; the dollars scale.
Activity 2 · Work Time
Use \(A = P e^{r t}\) with r = 0.07, t = 40.
Compute \(e^{0.07 \cdot 40} = e^{2.8}\). Round to 2 decimals.
Family A: P = $10,000. What is A?
Family B: P = $1,000,000. What is A?
What is the dollar gap (B − A) at year 0? At year 40?
What is the ratio B/A at year 0? At year 40?
Try Writing
From year 0 to year 40, the ratio ___ but the dollar gap ___.
10 min · Activity 2 Work Time. Leave on screen. Calculator must support \(e^{x}\) (TI: 2nd → ln; Desmos: type e^2.8).
Targets:
P1: \(e^{2.8} \approx 16.44\).
P2: 10,000 · 16.4446 ≈ $164,446.
P3: 1,000,000 · 16.4446 ≈ $16,444,647.
P4: Year 0 gap = $990,000. Year 40 gap ≈ $16,280,200. (~16.4× bigger.)
P5: Ratio is 100× at both year 0 and year 40 — identical. Multiplying both sides by the same constant preserves the ratio.
The big reveal: the multiplicative gap is preserved (the math is "fair") but the dollar gap explodes. That is what compound growth does to inequality — even at the same rate, even with no foul play.
Amplify · 5 inputs
Order: Text → Math Response (named answer1, answer2, answer3, answer4, answer5) → Note (CL).
content:
  when answer1.submitted and answer1.numericValue > 16.43 and answer1.numericValue < 16.45
    "Correct! e^2.8 ≈ 16.44. Every dollar invested becomes about $16.44 after 40 years at 7% continuous."
  when answer1.submitted and answer1.numericValue > 2.799 and answer1.numericValue < 2.801
    "Almost — that is just the exponent (r·t = 0.07·40 = 2.8). Now compute e^2.8 on the calculator."
  when answer1.submitted and answer1.numericValue > 14.879 and answer1.numericValue < 14.881
    "I see what happened — 14.88 is e^2.7. Check the exponent: 0.07 · 40 = 2.8, not 2.7."
  when answer1.submitted and not isBlank(answer1.latex)
    "Hmm — first compute the exponent r·t = 0.07 · 40 = 2.8. Then e^2.8 on the calculator. Target ≈ 16.44."
  otherwise ""
Problem 2: Family A — A = 10000 · e^2.8
content:
  when answer2.submitted and answer2.numericValue > 164400 and answer2.numericValue < 164500
    "Correct! Family A ends with about $164,446. Started with $10,000, multiplied by e^2.8 ≈ 16.4446."
  when answer2.submitted and answer2.numericValue > 16.43 and answer2.numericValue < 16.45
    "That is just the multiplier e^2.8 ≈ 16.44. Multiply by P = 10,000 to get the final amount."
  when answer2.submitted and answer2.numericValue > 27999 and answer2.numericValue < 28001
    "Almost — 28,000 is what you get from 10,000 · 2.8. The multiplier is e^2.8 ≈ 16.44, not 2.8."
  when answer2.submitted and not isBlank(answer2.latex)
    "Almost — multiply 10,000 by e^2.8 ≈ 16.4446. Target ≈ $164,446."
  otherwise ""
Problem 3: Family B — A = 1000000 · e^2.8
content:
  when answer3.submitted and answer3.numericValue > 16440000 and answer3.numericValue < 16450000
    "Correct! Family B ends with about $16,444,647 — 100× Family A's amount. Same multiplier; 100× principal; 100× result."
  when answer3.submitted and answer3.numericValue > 164400 and answer3.numericValue < 164500
    "That is Family A's answer. Family B started with $1,000,000 (100× larger). Multiply by e^2.8 ≈ 16.4446."
  when answer3.submitted and answer3.numericValue > 2799999 and answer3.numericValue < 2800001
    "Almost — 2,800,000 is 1,000,000 · 2.8. The multiplier is e^2.8 ≈ 16.4446, not 2.8."
  when answer3.submitted and not isBlank(answer3.latex)
    "Almost — multiply 1,000,000 by e^2.8 ≈ 16.4446. Target ≈ $16,444,647."
  otherwise ""
Problem 4: Dollar gap at year 40
content:
  when answer4.submitted and answer4.numericValue > 16270000 and answer4.numericValue < 16290000
    "Correct! Gap at year 40 ≈ $16.28 million — about 16.4× larger than the year-0 gap of $990,000."
  when answer4.submitted and answer4.numericValue > 989999 and answer4.numericValue < 990001
    "That is the year-0 gap. The question asks for year 40: subtract Family A's year-40 amount from Family B's."
  when answer4.submitted and answer4.numericValue > 16440000 and answer4.numericValue < 16450000
    "Almost — that is Family B alone. Subtract Family A's year-40 amount (~$164,446) to get the gap."
  when answer4.submitted and not isBlank(answer4.latex)
    "Hmm — Year-40 gap = (Family B at year 40) − (Family A at year 40) = 16,444,647 − 164,446 ≈ $16,280,200."
  otherwise ""
Problem 5: Ratio B/A at year 40
content:
  when answer5.submitted and answer5.numericValue > 99.5 and answer5.numericValue < 100.5
    "Correct! Ratio is 100× at both year 0 AND year 40. Same growth rate preserves the multiplicative gap."
  when answer5.submitted and answer5.numericValue > 16.43 and answer5.numericValue < 16.45
    "That is the growth multiplier e^2.8. The B/A ratio is different — divide Family B's amount by Family A's."
  when answer5.submitted and answer5.numericValue > 1 and answer5.numericValue < 2
    "Almost — the ratio is much larger than 1. Divide 16,440,000 by 164,400. What do you get?"
  when answer5.submitted and not isBlank(answer5.latex)
    "Hmm — ratio = 16,440,000 ÷ 164,400. The factor e^2.8 cancels: ratio = 1,000,000 ÷ 10,000 = 100."
  otherwise ""
Activity 2 · Synthesis5 min
The math is "fair." The dollars are not.
Year 0
Year 40
Multiplier
Family A (P = $10,000)
$10,000
$164,446
16.44×
Family B (P = $1,000,000)
$1,000,000
$16,444,647
16.44×
Dollar gap (B − A)
$990,000
$16,280,200
16.44×
Ratio B/A
100×
100×
(unchanged)
Same rate. Same time. Same e2.8. The ratio is preserved — that's just algebra. But the dollar gap grew by the same factor as everyone's wealth.
Why is the ratio preserved?Both sides got multiplied by the same number, \(e^{rt}\). \(\dfrac{P_B \cdot e^{rt}}{P_A \cdot e^{rt}} = \dfrac{P_B}{P_A}\). The factor cancels.
So what changed?The absolute dollar gap got multiplied by \(e^{rt} \approx 16.44\). $990,000 became roughly $16.28 million — not because anyone did anything wrong, but because compounding is a multiplicative operation, and a 100× gap on a bigger pile is a 100× bigger gap.
What can change the outcome?Look at the formula \(A = P e^{rt}\). Three letters move:
P — the starting principal. Who has one? When does the clock start?
r — the rate. Same for everyone here, but in real life: fees, redlining, predatory lending all bend it.
t — the time. Earlier start = more years of compounding. (Family B's kid invests at 18; Family A's kid pays off student debt until 30.)
click to advance discussion ▶
Try Saying
The thing that moved most was ___ because ___.
5 min. Sequence the discussion in order. The conceptual move: the same equation is "neutral" (same rate, same time) and yet produces a wildly different real-world outcome — because the inputs were not the same to begin with.
The third bullet teases the agency move on the next slide. Don't resolve interventions yet — just name the levers (P, r, t).
Agency Move7 min
What policy starts the clock earlier?
The math says: if both families have the same P, the gap stays a gap. The wrench: change someone's starting P, or start their t earlier. Here are five real interventions with measured effect sizes. Read them, then pick one to defend.
CT Baby Bonds (2023–)
$3,200 → projected $11k–$24k at age 18
Connecticut invests $3,200 at birth for every child born to a Medicaid family. ~16,000 children seeded in FY 2024 alone. Locked until 18, then can be used for education, business, home, or retirement.
Federal Baby Bonds (Booker / Pressley)
Modeled to close ~92% of racial wealth gap at 18
$1,000 at birth + up to $2,000/year, scaled by family income. Released at 18 for wealth-building uses. Hamilton/Darity model. Reintroduced annually since 2018; not yet passed.
2021 Expanded Child Tax Credit
Cut child poverty 43% in 2021
Monthly cash payments to families with children. Lapsed after one year; child poverty climbed back up in 2022. Not the same as a wealth-builder, but it changes P for households that have nothing to invest.
MA BabySteps 529 (2020–)
$50 seed at birth + $10/mo for SNAP families
Massachusetts adds $50 to a 529 college account when families open one in the first year. Tiny seed, but compounds for 18 years and gets families into the savings system early.
Estate-tax threshold restoration
Threshold: $675k (2000) → $13.61M (2024)
In 2000, estates over $675K paid the estate tax (top rate 55%). In 2024, only estates over $13.61M pay (top rate 40%). Returning the threshold lower would catch more multi-generational wealth before it compounds again.
Your alternative
Defend it with the math
If none of the above moves the lever you care about, propose your own. Tie it back to P, r, or t in the formula \(A = P e^{rt}\).
Try Saying
I would push for ___ because it changes ___ in the formula \(A = P e^{r t}\), and the math says ___.
7 min. Popcorn discussion, not a project. Read the cards aloud (or assign one per pair, 2 min). Then pull 4–5 voices in 5 min using the sentence frame.
Don't make students share if they pass. The opt-out matters — some students may have personal experience with debt or no inheritance. Frame the question as "which lever, mathematically, do you want pulled?"
Sample student answers (don't reveal these — press for them):
"Federal baby bonds change P for kids who have $0 in the formula. Without P, the formula gives 0 forever."
"The estate-tax change works on Family B's t — it caps how much of the compounded pile passes to the next generation, so the clock has to restart."
"The expanded CTC doesn't go into a 529, so it's not really compounding — but it's the only one that families with no margin can actually receive."
No "right answer." The math is neutral; the choice of intervention is the wrench.
Lesson Synthesis3 min
What is e?
How is e like π?Both are irrational constants. Decimals never repeat or terminate. Both show up in formulas across math, science, and engineering.
How is e different from π?π ≈ 3.14 comes from circle geometry. e ≈ 2.718 comes from compounding — the natural ceiling when something grows in proportion to its current size.
What does \(A = Pe^{rt}\) tell us about gaps?When everyone gets the same r and t, the multiplicative ratio between any two people's wealth is preserved — but the dollar gap is multiplied by \(e^{rt}\). For us today: a $990k gap became a $16.3M gap with no foul play, just compounding.
click to advance ▶
By the end of today, I can:
· Recognize e as a number (≈ 2.718) like π.
· Read \(\left(1+\tfrac{1}{n}\right)^{n}\) and explain why it approaches e as n grows.
· Use \(A = P e^{r t}\) to compute continuously compounded amounts.
· Explain how the same growth rate preserves a ratio while multiplying a dollar gap.
3 min. Click through the three Q's. The SWBAT is the confirmation, not the preview — students just did all four bullets, so checking them off lands.
Cool-Down4 min
Exit Ticket
A grandparent invests $2,500 for their newborn at the same continuous rate of 7%. The child does not touch it for 40 years.
Answer briefly. Calculator OK.
Using \(A = P e^{r t}\) with P = 2500, r = 0.07, t = 40, compute A. Round to the nearest dollar.
In one sentence: what is the number e?
If a second child receives $0 at birth and invests $0 for 40 years at the same rate, what is A?
Cool-Down · 4 min. Closes the loop on the lesson and on the agency move. Problem 3 is the trap question — \(0 \cdot e^{rt} = 0\), the formula has no growth without a non-zero P. That's why "starting principal" matters and why baby bonds & CTC change the input that the formula multiplies, not the multiplier itself.
Targets: P1: \(2500 \cdot e^{2.8} \approx \$41{,}094\). P2: irrational, ≈ 2.718, the limit of compounding. P3: $0 — multiplying anything by 0 leaves 0.
Amplify · Cool-Down Setup
P1: Text → Math Response (answer1) → Note. Format: Example: 41094.
P2: Text → Text Response (answer2) → Note (no CL grading; observation only).
P3: Text → Math Response (answer3) → Note. Format: Example: 0.
Problem 1: A = 2500 · e^2.8
content:
  when answer1.submitted and answer1.numericValue > 41080 and answer1.numericValue < 41110
    "Correct! 2500 · e^2.8 ≈ $41,094. Notice — same multiplier (16.44) as Family A and Family B today."
  when answer1.submitted and answer1.numericValue > 16.43 and answer1.numericValue < 16.45
    "That is just e^2.8. Multiply by P = 2500 to get the final amount."
  when answer1.submitted and answer1.numericValue > 6999 and answer1.numericValue < 7001
    "Almost — 7000 is 2500 · 2.8. The multiplier is e^2.8 ≈ 16.44, not 2.8."
  when answer1.submitted and answer1.numericValue > 164300 and answer1.numericValue < 164500
    "That is Family A's answer (P = 10,000). The grandparent invested $2,500. Try 2500 · e^2.8."
  when answer1.submitted and not isBlank(answer1.latex)
    "Almost — A = 2500 · e^(0.07·40) = 2500 · e^2.8. Target ≈ 41,094."
  otherwise ""
Problem 2: What is e? [Text Response]
content:
  when answer2.submitted and not isBlank(answer2.content)
    "Thank you — share your sentence at the start of next class."
  when answer2.submitted and isBlank(answer2.content)
    "Please write one sentence describing the number e."
  otherwise ""
Problem 3: A = 0 · e^2.8
content:
  when answer3.submitted and answer3.numericValue = 0
    "Correct! 0 · e^2.8 = 0. The formula needs a non-zero P. This is why the starting principal — and the policies that create one — matter."
  when answer3.submitted and answer3.numericValue > 16.43 and answer3.numericValue < 16.45
    "That is the multiplier e^2.8. But you are multiplying it by 0. Anything times 0 is 0."
  when answer3.submitted and not isBlank(answer3.latex)
    "Hmm — 0 multiplied by anything is 0. So 0 · e^2.8 = ?"
  otherwise ""
Lesson Summary
The number e — and what it does to gaps
What e is
An irrational constant ≈ 2.71828. It is the limit of \(\left(1+\tfrac{1}{n}\right)^{n}\) as n grows. It shows up wherever something grows in proportion to its current size.
What \(Pe^{rt}\) does
Continuous compounding. Multiplies your principal by \(e^{rt}\). Same rate & time = same multiplier — ratios are preserved.
What it does to gaps
A 100× head-start, compounded at 7% real for 40 yrs, becomes a $16M dollar gap. To change the outcome, change P or t — not the rate.
The rate question to leave with
If we cannot change r (the market does that), and we will not change t from 40 years (a career)… which policy will we push to change P?
Lesson Summary slide. Read the three colored cards, then leave the orange "rate question" up while students pack up. The agency move from slide 11 lives in this orange box — it's the take-home.
Next lesson: students will revisit logarithms with base e (the natural log) to invert this formula and solve for t — "how many years until I have X?"